
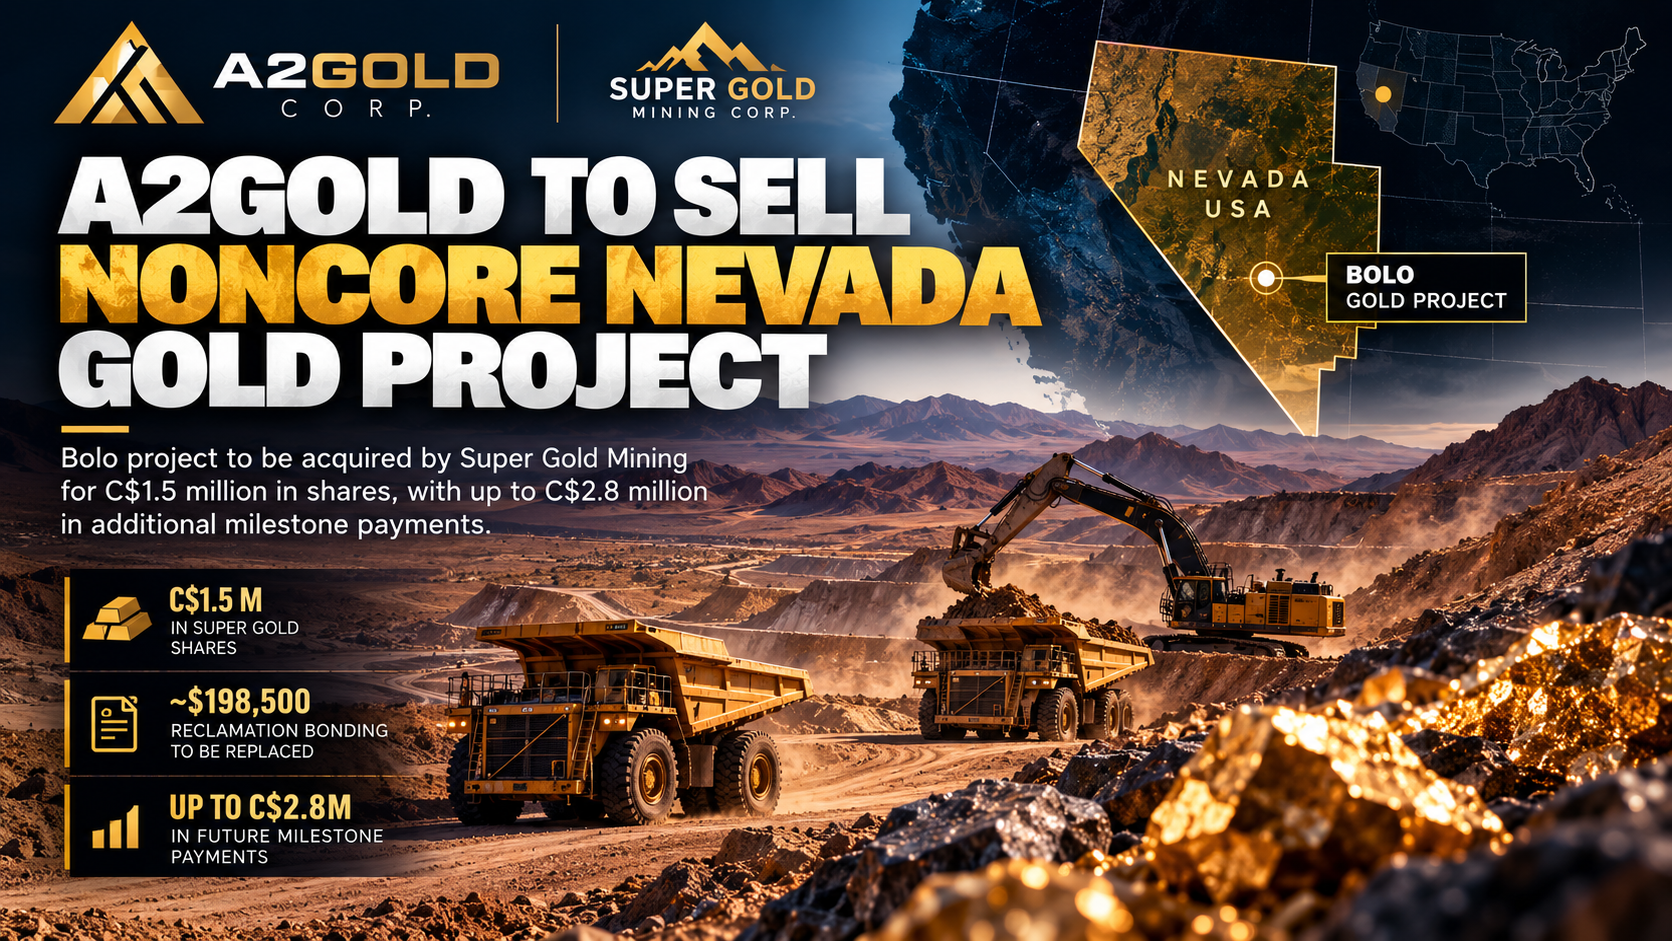
A2Gold Moves to Monetize Non-Core Nevada Gold Asset
Canadian-listed gold and silver exploration company A2Gold Corp. has agreed to sell its 100% interest in the Bolo Gold Project in Nevada to Super Gold Mining Corp., in a transaction designed to unlock value from a non-core asset while allowing A2Gold to concentrate its resources on its principal projects.
Under the definitive Mining Property Purchase and Sale Agreement announced October 29, A2Gold will receive C$1.5 million in Super Gold shares, along with the replacement of approximately US$198,500 in reclamation bonding currently associated with Bolo.
The transaction also gives A2Gold the possibility of receiving as much as C$2.4 million in future mineral-resource milestone payments, plus another C$400,000 if a qualifying preliminary economic assessment is completed.
In total, the contingent consideration could reach C$2.8 million, in addition to the initial C$1.5 million share consideration.
For A2Gold, the deal is less about abandoning gold exploration and more about deciding where its capital and technical expertise can potentially generate the greatest shareholder value.
What Is the Bolo Project?
The Bolo Gold Project is located in Nye County, Nevada, in the United States.
According to A2Gold, the property consists of 187 unpatented lode mining claims together with the Uncle Sam patented mining claim.
Rather than continuing to allocate exploration and holding costs to the property, A2Gold is transferring the project to Super Gold, which will assume responsibility for advancing Bolo.
That allows A2Gold to retain an economic interest in the property’s future without continuing to carry the same direct exploration and reclamation obligations.
The company says the transaction fits its strategy of monetizing non-core assets while maintaining exposure to potential future discoveries.
The Initial Payment Is More Than Just Cash
One of the most important details of the transaction is that A2Gold is not receiving C$1.5 million in cash.
Instead, Super Gold will issue A2Gold 3.75 million common shares, valued for the transaction at C$0.40 per share.
That produces a deemed value of C$1.5 million.
The distinction is important for investors because the value of those shares ultimately depends on Super Gold’s future development and financing plans.
The shares will also be subject to contractual resale restrictions.
Under the agreement, portions of the share consideration become available for resale over time following Super Gold’s planned going-public transaction.
A2Gold is therefore effectively exchanging direct ownership of a mineral exploration project for an equity position in the company taking that project forward.
Reclamation Costs Are Another Part of the Deal
Mining projects carry environmental and reclamation obligations that can tie up capital even before a mine is developed.
At Bolo, Super Gold has agreed to replace approximately US$198,500 in reclamation bonding.
That allows A2Gold’s existing reclamation funds associated with the project to be released.
For a junior or exploration-focused mining company, releasing capital that is otherwise tied up in reclamation security can be strategically important.
The transaction also calls for Super Gold to reimburse A2Gold for applicable claim-maintenance fees paid during the current year.
This means the economic benefit to A2Gold is not limited to the headline C$1.5 million share consideration.
A2Gold Keeps a Stake in Bolo’s Future
The deal becomes more interesting when the contingent payments are examined.
Super Gold must undertake exploration and technical work intended to support an initial NI 43-101 mineral resource estimate for Bolo within two years of closing.
The amount A2Gold could eventually receive depends on the size of the future gold-equivalent resource established at the project.
The milestone structure rises with the size of the resource:
Future Gold-Equivalent Resource
Cumulative Payment
200,000–399,999 oz
C$500,000
400,000–599,999 oz
C$800,000
600,000–799,999 oz
C$1.1 million
800,000–999,999 oz
C$1.5 million
1,000,000+ oz
C$2.4 million
A2Gold could also receive an additional C$400,000 if a future preliminary economic assessment meets the conditions established in the agreement, including a minimum resource threshold and specified economic criteria.
That structure gives A2Gold a form of continuing exposure to exploration upside without having to finance the project itself.
Why Sell a Gold Project If Gold Is Valuable?
At first glance, selling a gold project might seem counterintuitive.
Gold remains one of the world’s most closely watched commodities, and exploration companies can generate substantial value when an early-stage project develops into a significant resource.
But exploration companies face a basic constraint:
capital is limited.
Every dollar invested in one project is a dollar that cannot be deployed somewhere else.
The strategic question is therefore not simply whether Bolo has geological potential.
It is whether Bolo represents the best use of A2Gold’s capital and technical resources.
The company says it believes its Eastside and Taylor projects offer greater opportunities to create shareholder value.
By selling Bolo, A2Gold can concentrate its attention on those core assets while retaining a financial interest if the Nevada project ultimately proves more valuable than currently established.
Super Gold Gets a Project It Can Advance
The transaction also illustrates the role that smaller mining companies play in the exploration ecosystem.
A project can be considered non-core by one company while being strategically important to another.
For Super Gold, Bolo provides an opportunity to acquire a defined exploration asset and pursue the next stage of technical work.
The company will be responsible for advancing exploration and working toward a future mineral-resource estimate.
If successful, that work could establish a larger resource base and potentially create the foundation for a preliminary economic assessment.
That is where the contingent-payment structure becomes significant.
A2Gold effectively retains a financial interest in the upside without maintaining direct project ownership.
The Going-Public Question

There is another important condition attached to the transaction.
Super Gold has agreed to use commercially reasonable efforts to complete a going-public transaction within 12 months of closing, and no later than 18 months, subject to the agreement’s provisions.
If Super Gold has not completed such a transaction within 12 months, A2Gold becomes entitled to a C$200,000 cash payment.
If the going-public transaction has not occurred within 18 months, A2Gold may, subject to the agreement’s conditions and cure provisions, elect to have the Bolo project reconveyed.
This gives A2Gold additional protection if Super Gold is unable to execute its planned corporate transition.
Protection if Bolo Is Sold Again
A2Gold has also negotiated protection against a scenario in which Super Gold quickly monetizes Bolo through another transaction.
If, during the applicable milestone period, Super Gold enters into a qualifying transaction involving Bolo with consideration attributable to the project of at least C$25 million, the maximum C$2.4 million mineral-resource milestone and C$400,000 PEA payment would be deemed earned.
A2Gold would then be entitled to receive the unpaid balance of the aggregate C$2.8 million contingent consideration.
The agreement also contains additional protections covering certain dispositions of Bolo during the first two years after closing.
For A2Gold, that means the transaction is structured to preserve some of the project’s potential future value even after ownership changes hands.
What Happens Next?
The transaction is not yet closed.
A2Gold expects closing to occur within the next few weeks, subject to satisfaction or waiver of several conditions.
Among them are:
- Establishment and acceptance of replacement reclamation bonding.
- Release of A2Gold’s existing reclamation bond.
- Approval of the transfer of the applicable Plan of Operations to Super Gold’s U.S. subsidiary or designated operator.
- Delivery of the required Cordex estoppel certificate.
- Completion of customary title and closing documentation.
Until those conditions are satisfied, the transaction remains subject to the closing process outlined in the agreement.
What the Deal Says About Junior Mining
The A2Gold-Bolo transaction highlights a broader trend in the junior mining sector: portfolio rationalization.
Exploration companies frequently accumulate multiple properties during periods of aggressive growth.
Over time, management teams must determine which assets deserve additional drilling, engineering, permitting and capital.
Selling a non-core property can therefore be a strategic move rather than a sign that management believes the asset has no value.
In this case, A2Gold is effectively saying:
Bolo may still have value—but someone else can spend the money needed to find out.
That is a very different proposition from writing off an exploration asset entirely.
Why the Nevada Deal Matters to African Mining
Although Bolo is located in Nevada, the transaction carries lessons for Africa’s mining sector.
Across Africa, exploration companies hold large portfolios of early-stage gold, copper, lithium, graphite and other mineral projects.
Some properties may eventually become major mines.
Others may require years of drilling and millions of dollars before their commercial potential becomes clear.
The A2Gold model demonstrates one way to manage that uncertainty.
A company can transfer a non-core project to a better-capitalized or more focused explorer while retaining:
equity exposure,
milestone payments,
economic-assessment payments,
and contractual protections against a future sale.
That can create a bridge between exploration ownership and capital efficiency.
For African juniors, such structures could become increasingly relevant as financing conditions, commodity cycles and investor expectations evolve.
The Gold Story Is Not Just About Production
Mining headlines often focus on producing mines.
But some of the most important financial decisions happen much earlier.
A project has to move through exploration, resource definition, economic assessment, permitting, financing and construction before it can become a producing mine.
At each stage, ownership can change.
Bolo’s sale is an example of that process.
A2Gold is effectively transferring the next stage of exploration risk to Super Gold while retaining potential financial participation if the project delivers a larger resource or advances toward economic development.
The transaction therefore represents a bet on capital specialization.
A2Gold believes its own capital and technical resources can potentially generate more value elsewhere.
Super Gold believes Bolo is worth the investment required to advance it.
Both companies are effectively making different bets on the same mineral property.
The Bottom Line
A2Gold’s sale of Bolo is a relatively small transaction compared with major mining acquisitions, but its structure offers an interesting look at how exploration companies manage portfolios.
At closing, A2Gold is set to receive:
C$1.5 million in Super Gold shares
plus the release of approximately:
US$198,500 in reclamation bonding
while retaining potential future consideration of up to:
C$2.8 million.
The larger strategic objective is clear.
A2Gold wants to concentrate its capital and technical resources on Eastside and Taylor, while allowing another company to take responsibility for advancing Bolo.
For Super Gold, the challenge now is execution.
The value of the transaction will ultimately depend on what exploration discovers at Bolo, whether a compliant mineral resource can be established, whether the project can demonstrate economic potential and whether Super Gold can successfully execute its corporate plans.
For A2Gold, the transaction creates something increasingly valuable in the exploration business:
capital flexibility without completely surrendering future upside.
And for investors watching the global mining sector, Bolo offers another reminder that the value of a mineral property can change dramatically depending on who owns it, who funds it and who has the technical capacity to advance it.
This article is based on A2Gold’s October 29, 2026 transaction announcement. The sale remains subject to closing conditions, and future milestone payments depend on exploration results and other contractual requirements. It should not be interpreted as investment advice.
Leave a Reply